Why business insurance in Fresno, CA is more complex than most owners expect
Business insurance in Fresno, CA is not a one-size-fits-all purchase. Fresno sits at the intersection of Central Valley agriculture, a growing logistics and distribution sector, a food-processing industry, and a downtown small-business scene that has been expanding for years. Each of those environments carries different exposures, different carrier appetites, and very different price points. If you have ever tried to shop coverage on your own or gone straight to a single carrier, you already know how confusing the process can get. This post breaks down what Fresno small businesses actually need to know, and why working with an independent agent almost always produces a better outcome.
What "business insurance" actually means for a Fresno small business
The term gets used loosely, but business insurance is really a bundle of several distinct coverages. Most small businesses need more than one policy, and some policies can be packaged together to save money. Here are the building blocks that come up most often for Fresno-area businesses:
- General liability covers bodily injury or property damage you cause to a third party. If a customer slips on your floor or you accidentally damage a client's property on a job site, this is the policy that responds. Learn more on our general liability insurance page.
- Commercial property covers your building, equipment, inventory, and furnishings against fire, vandalism, theft, and certain weather events. In the Central Valley, heat-related equipment failures and the occasional wind event are real concerns.
- Business owner's policy (BOP) packages general liability and commercial property into one policy, usually at a lower combined premium than buying each separately. It is a strong starting point for most small businesses with under a few million in revenue.
- Workers' compensation is mandatory in California for any business with one or more employees. The state has some of the strictest enforcement in the country, and penalties for non-compliance are steep.
- Commercial auto : if your employees drive for work purposes in any vehicle, your personal auto policy will not cover a claim that arises during business use.
- Professional liability (errors and omissions) is important for consultants, accountants, designers, and any professional who gives advice for a fee. A dissatisfied client can file a claim even when you did nothing wrong.
- Cyber liability is increasingly relevant for any business that stores customer data, processes payments online, or uses cloud-based software. Data breach costs in California average well over $200,000 for a small business once you add up notification, legal, and recovery expenses.
Most businesses need at least three or four of these coverages working together. The exact combination depends on your industry, your lease terms, your payroll, and your exposure to lawsuits.
Fresno-specific risks that affect your coverage needs
Insurance is priced and structured around risk, so local conditions matter a great deal. A few factors specific to Fresno and the broader San Joaquin Valley shape what coverage you need and what it will cost.
Wildfire and smoke proximity
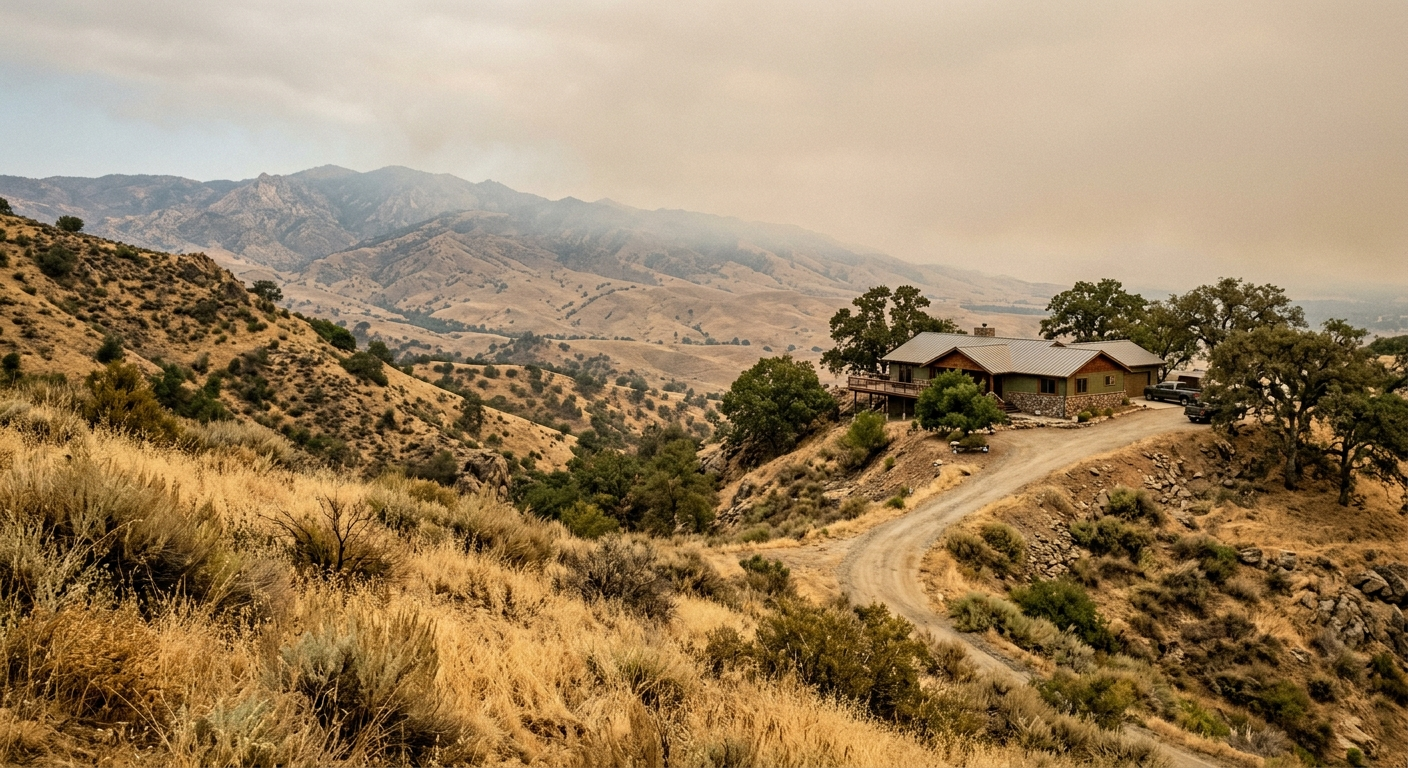
The Sierra Nevada foothills east of Fresno have produced some of the most damaging wildfires in California history. Businesses in foothill communities near Fresno, including areas around Shaver Lake, Friant, and Auberry, face elevated commercial property premiums and in some cases limited carrier options. Even businesses located in the city of Fresno can face smoke-related inventory damage, HVAC damage, and business interruption losses during a bad fire season. Your business interruption policy is what covers lost income when you have to close or reduce operations due to a covered event.
Extreme heat
Fresno regularly records triple-digit temperatures from late June through September. Refrigeration-dependent businesses (restaurants, grocery, food processing, floral, pharma distribution) face real exposure when HVAC or cooling equipment fails. Equipment breakdown coverage, which can be added to many commercial property policies, specifically addresses mechanical failure and is worth a serious look if your operation depends on refrigeration.
Agricultural supply-chain exposure
Many Fresno businesses are directly or indirectly tied to agriculture. A crop failure, a processing disruption, or a contamination event upstream can affect revenue significantly. If your business revenue is tied to agricultural production cycles, a standalone business interruption policy or contingent business interruption endorsement is worth discussing with your agent.
Theft and crime
Like most metro areas, Fresno sees property crime rates that affect certain business districts. If you carry inventory, tools, or cash on premises, a commercial crime policy fills the gap that standard commercial property policies leave open, particularly for employee dishonesty and theft by third parties.
Why an independent agent beats a captive agent for Fresno businesses
This is the part that makes the biggest practical difference for most business owners. When you call a captive agent (one who works exclusively for a single carrier like State Farm or Allstate), that agent can only offer you what their one carrier sells. If that carrier has tightened its appetite for restaurants, contractors, or any industry that happens to describe your business, your options are limited to whatever that carrier will write, at whatever price they set.
An independent agent represents multiple carriers. At McCarty Insurance Agency, that means we can shop your risk across several A-rated markets and find the carrier that is genuinely competitive for your specific business type, your claims history, and your location in the Fresno area. The difference in annual premium for a comparably structured policy can easily run into the hundreds or thousands of dollars depending on your industry.
There is also a coverage quality dimension. Two policies can look identical on price but have meaningfully different exclusions, sublimits, or claims-handling reputations. An independent agent reads the policy language, not just the summary page, and can explain what you are actually buying.
For a closer look at how independent and captive agents differ structurally, our post on independent vs. captive insurance agents walks through the key distinctions.
California-specific rules every Fresno business owner should know
California adds a layer of legal requirements and regulatory nuance that affects your coverage decisions directly.
Workers' compensation is not optional
California Labor Code requires every employer with at least one employee to carry workers' comp, no exceptions. The California Department of Industrial Relations actively audits compliance, and operating without coverage can result in fines of up to $10,000 per violation , stop-work orders, and personal liability for the business owner. If you use subcontractors, make sure they carry their own coverage, or you may be considered their employer under California law. Our page on workers' compensation insurance covers the basics.
AB 5 and the contractor classification issue
California's AB 5 law made it significantly harder to classify workers as independent contractors. If workers you previously treated as contractors are now legally considered employees, your workers' comp and general liability exposure changes. This is an area where a conversation with both your insurance agent and a business attorney is worth the time.
CCPA and data privacy liability
The California Consumer Privacy Act gives consumers rights over their personal data. If your business collects customer information (which almost every business does in some form), a data breach or improper handling claim can trigger significant liability. Cyber liability coverage is the policy designed to address this, and it has moved from optional to genuinely necessary for most businesses that collect payment card data or customer records. Our cyber liability guide for small businesses explains what the policy actually covers.
Commercial lease requirements
Most commercial leases in Fresno require tenants to carry a minimum amount of general liability coverage, often $1,000,000 per occurrence and $2,000,000 aggregate , and to name the landlord as an additional insured. Before you sign a lease, have your agent review the insurance requirements section so you are not scrambling to meet those specs at signing.
How much does business insurance cost in Fresno?
There is no honest single-number answer here because premiums vary so widely by industry, revenue, payroll, square footage, and claims history. That said, here are some realistic reference points for small businesses in the Fresno area:
- General liability only (low-risk business, e.g., consulting or retail) : roughly $500 to $1,200 per year for a $1M/$2M policy.
- BOP (general liability plus commercial property, small office or retail) : roughly $1,000 to $2,500 per year depending on square footage and building value.
- Workers' compensation (California) : calculated per $100 of payroll, with rates varying dramatically by job classification. A clerical employee might run $0.40 per $100 of payroll , while a roofing employee could exceed $20.00 per $100 .
- Cyber liability : a basic policy for a small business often runs $800 to $2,000 per year for $1M in coverage, though premiums have risen in recent years with the increase in ransomware claims.
- Professional liability / E&O : ranges from roughly $700 to $3,000 per year depending on your profession and revenue.
These are ballpark figures. The only way to get a real number is to get quotes from multiple carriers based on your actual business details, which is exactly what an independent agent does for you.
Common mistakes Fresno business owners make with insurance
After years of working with small businesses across Fresno, Clovis, and the surrounding Central Valley communities, we see the same mistakes come up repeatedly.
- Assuming a home-based business is covered under homeowners : standard homeowners policies exclude business property and business liability. If you run any kind of business from home, you need either a home-based business endorsement or a separate commercial policy.
- Skipping business interruption coverage : property damage is visible and easy to think about. Lost income while you are closed for repairs is less visible but often the more financially damaging part of a major loss.
- Underinsuring commercial property : insuring your building or equipment for less than replacement cost saves premium dollars in the short term and creates a coverage gap at the worst possible moment. Construction costs in California have climbed significantly over the past several years, and policies that have not been updated to reflect current replacement costs can leave you short.
- Not reviewing coverage annually : if your revenue, payroll, location, or equipment changes, your coverage needs to change with it. A policy that was right for your business two years ago may have real gaps today.
- Treating the cheapest quote as the best quote : the cheapest policy is often cheap for a reason. An independent agent can show you side-by-side comparisons of what is actually included in each option.
Get the right business insurance coverage for your Fresno company
McCarty Insurance Agency is an independent agency serving Fresno, Clovis, Madera, and communities throughout the Central Valley. Being independent means we work for you, not for any single carrier. We compare options across multiple A-rated markets to find coverage that actually fits your business, at a price that makes sense for your budget.
Whether you are just starting out and need a basic BOP, or you are an established business that has outgrown your current coverage and needs a full review, our team is ready to help. You can reach us at (559) 324-1421 or contact us online to get started. We serve businesses across Fresno and the broader San Joaquin Valley, and we are happy to explain every option in plain language before you commit to anything.